FHLBank Pittsburgh Announces Third Quarter 2026 Operating Highlights
The Federal Home Loan Bank of Pittsburgh (FHLBank) announced today unaudited financial results for the third quarter
Press Release Disclaimer: This is a press release distributed through the XPR Media network. It has not been independently verified by our newsroom.


The Federal Home Loan Bank of Pittsburgh (FHLBank) announced today unaudited financial results for the third quarter and nine months ended September 30, 2026.
This press release features multimedia. View the full release here: https://www.businesswire.com/news/home/20261021187619/en/
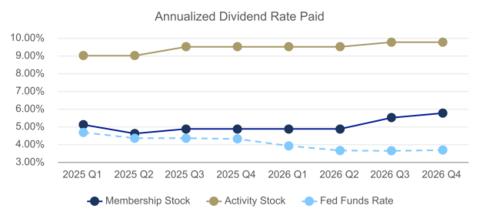
The table presents the annualized dividend rate paid over eight quarters, including the dividend to be paid October 23, 2026; these dividends are based on stockholders’ average balances for the previous quarter. Note: “Fed funds rate” refers to the average effective federal funds rate during the period in which the dividend rates were calculated.
Financial Highlights:
- Third quarter net income of $134.7 million
- Third quarter net interest income of $163.2 million
- Declared a third quarter dividend on activity stock at 9.75% annualized
- Declared a third quarter dividend on membership stock at 5.75% annualized
Credit Product Balances:
- Advances at $87.0 billion
- Mortgage loans held for portfolio, net at $5.7 billion
- Standby letters of credit at $30.6 billion
Community Product Assessment and Contributions:
- Statutory Affordable Housing Program (AHP) third quarter assessment of $15.0 million for use in 2027
- Third quarter voluntary contributions to community products of $7.5 million, including a supplemental voluntary contribution to AHP of $0.8 million
Statements of Income
FHLBank’s net income totaled $134.7 million for the third quarter of 2026, compared to $97.1 million for the same prior-year period. The $37.6 million increase in net income was driven primarily by the following:
-
Net interest income was $163.2 million for the third quarter of 2026, an increase of $18.2 million from $145.0 million during the same prior-year period.
- Interest income was $1,240.3 million for the third quarter of 2026, compared to $998.8 million in the same prior-year period. This increase was driven by higher average assets partially offset by lower average short-term interest rates.
- Interest expense was $1,077.1 million for the third quarter of 2026, compared to $853.8 million in the same prior-year period. This increase was the result of higher average consolidated obligations partially offset by lower average short-term interest rates.
- Noninterest income (loss) was $24.7 million for the third quarter of 2026, compared to $3.8 million in the same prior-year period. This $20.9 million increase was due primarily to valuation changes in FHLBank’s economic derivative portfolio.
- Other expense was $28.8 million for the third quarter of 2026, compared to $31.2 million in the same prior-year period. This $2.4 million decrease was due primarily to lower assessments from the Finance Agency and the Office of Finance.
- Voluntary contributions to community products were $7.5 million, including a supplemental voluntary contribution to AHP of $0.8 million, for the third quarter of 2026, a decrease of $1.8 million compared to $9.3 million in the same prior-year period.
- Statutory AHP assessments were $15.0 million as a result of third quarter 2026 earnings, compared to $10.8 million in the same prior-year period.
FHLBank’s net income totaled $326.4 million for the nine months ended September 30, 2026, relatively flat compared to $328.9 million for the same prior-year period, driven primarily by the following:
-
Net interest income was $444.1 million for the nine months ended September 30, 2026, a decrease of $40.9 million from $485.0 million during the same prior-year period.
- Interest income was $3,030.2 million for the nine months ended September 30, 2026, compared to $3,312.7 million in the same prior-year period. This decrease was driven by lower average short-term interest rates partially offset by higher average assets.
- Interest expense was $2,586.1 million for the nine months ended September 30, 2026, compared to $2,827.7 million in the same prior-year period. This decrease was the result of lower average short-term interest rates partially offset by higher average consolidated obligations.
- Noninterest income was $33.9 million for the nine months ended September 30, 2026, compared to $5.2 million in the same prior-year period. This $28.7 million increase was due primarily to valuation changes in FHLBank’s economic derivative portfolio.
- Other expense was $89.1 million for the nine months ended September 30, 2026, compared to $94.7 million in the same prior-year period. The decrease of $5.6 million was due primarily to lower assessments from the Finance Agency and the Office of Finance.
- Voluntary contributions to community products were $21.8 million, including a supplemental voluntary contribution to AHP of $2.3 million, for the nine months ended September 30, 2026, a decrease of $6.3 million compared to $28.1 million in the same prior-year period. FHLBank committed to making voluntary contributions of at least 5% of the prior year’s pre-assessment net income to voluntary community products, a commitment target of at least $25.8 million. See FHLBank’s Current Report on Form 8-K filed with the Securities and Exchange Commission (SEC) on August 19, 2026 for a description of the Board of Directors’ approval on August 14, 2026 of an increase of $20 million in the pool of funds anticipated to made available for the 2026 funding round for FHLBank’s Voluntary Housing Grant (VHG), increasing the total allocation expected to be awarded in VHG from $13.5 million to $33.5 million.
- Statutory AHP assessments were $36.4 million based on earnings for the nine months ended September 30, 2026, compared to $36.6 million in the same prior-year period.
Statements of Condition
At September 30, 2026, total assets were $126.0 billion, compared with $73.3 billion at December 31, 2025. The increase was primarily due to an increase in advances, which totaled $87.0 billion at September 30, 2026, compared to $36.8 billion at year-end 2025. Demand for advances continues to fluctuate based on members’ liquidity management practices, which are influenced by their loan demand, deposit balances and investment activities.
Total capital at September 30, 2026, was $6.7 billion, compared to $4.6 billion at December 31, 2025, including retained earnings of $2.4 billion at September 30, 2026, compared to $2.2 billion at December 31, 2025. At September 30, 2026, FHLBank remained in compliance with all regulatory capital requirements.
Quarterly Dividends
The Board of Directors declared a dividend on subclass B1 (membership) stock equal to an annual yield of 5.75% and a dividend on subclass B2 (activity) stock equal to an annual yield of 9.75%. Dividends paid will be calculated on stockholders’ average balances during the period July 1, 2026, to September 30, 2026, and be credited to stockholders’ accounts on October 23, 2026.
The table presents the annualized dividend rate paid over eight quarters, including the dividend to be paid October 23, 2026; these dividends are based on stockholders’ average balances for the previous quarter.
Detailed financial information about the third quarter and nine months ended September 30, 2026, financial results will be available in FHLBank’s Quarterly Report on Form 10-Q, which FHLBank anticipates filing no later than November 11, 2026.
About FHLBank Pittsburgh
FHLBank Pittsburgh provides reliable funding and liquidity to its member financial institutions, which include commercial and savings banks, community development financial institutions, credit unions and insurance companies in Delaware, Pennsylvania and West Virginia. FHLBank products and resources help support community lending, housing and economic development. As one of 11 Federal Home Loan Banks established by Congress, FHLBank has been an integral and reliable part of the financial system since 1932. Learn more by visiting www.fhlb-pgh.com.
This document contains “forward-looking statements” – that is, statements related to future, not past or current, events. In this context, forward-looking statements often address FHLBank’s expected future business and financial performance, and often contain words such as “expect,” “anticipate,” “intend,” “plan,” “believe,” “seek,” “will” or similar expressions. Forward-looking statements by their nature address matters that are, to different degrees, uncertain and involve risk.
Actual performance or events may differ materially from that expected or implied in forward-looking statements because of many factors. Such factors may include, but are not limited to, economic and market conditions, including, but not limited to, conditions in real estate, credit and mortgage markets; volatility of market prices, rates and indices related to financial instruments; natural or man-made disasters, pandemics, climate change, conflicts or terrorist attacks or other geopolitical events; political uncertainties related to global trade policies, supply chain disruptions and tariff tensions; executive, legislative, regulatory, and judicial events and actions that affect FHLBank, its members, counterparties, other Federal Home Loan Banks or investors in Federal Home Loan Bank debt; risks related to FHLBank’s investments, including investments in mortgage-backed securities; changes in the assumptions used to estimate credit losses; changes in FHLBank’s: credit rating, capital structure, capital requirements, membership composition, membership’s demand for advances and other products, and competitive environment; changes in expectations regarding FHLBank’s payment of dividends; increases or decreases in advance prepayments; changes in investor demand for Federal Home Loan Bank debt or in the ratings of Federal Home Loan Bank System debt; changes in FHLBank’s ability to introduce new products and services to meet market demand and to manage successfully the risks associated with new products and services; FHLBank’s ability to enter into financial instruments to meet its investment, balance sheet and risk management goals; disruptions in the capital markets; the ability of each of the other Federal Home Loan Banks to repay the principal and interest on consolidated obligations for which it is the primary obligor and with respect to which FHLBank has joint and several liability; technology and cybersecurity risks (including cybersecurity risk driven by artificial intelligence); and timing and volume of market activity. Additional risks that might cause FHLBank’s results to differ from these forward-looking statements are provided in detail in FHLBank’s filings with the SEC, which are available at www.sec.gov. Forward-looking statements speak only as of the date made, and FHLBank has no obligation, and does not undertake publicly, to update or revise any forward-looking statement for any reason.
|
Unaudited Condensed Statements of Condition and Income (in millions)
|
||||||||
|
Condensed Statement of Condition |
|
September 30, 2026 |
|
December 31, 2025 |
||||
|
ASSETS: |
|
|
|
|
||||
|
Cash and due from banks |
|
$ |
33.9 |
|
|
$ |
32.6 |
|
|
Investments |
|
|
32,321.2 |
|
|
|
30,518.6 |
|
|
Advances |
|
|
86,987.4 |
|
|
|
36,820.0 |
|
|
Mortgage loans held for portfolio, net |
|
|
5,707.8 |
|
|
|
5,220.3 |
|
|
All other assets |
|
|
900.4 |
|
|
|
725.7 |
|
|
Total assets |
|
$ |
125,950.7 |
|
|
$ |
73,317.2 |
|
|
|
|
|
|
|
||||
|
LIABILITIES: |
|
|
|
|
||||
|
Consolidated obligations |
|
$ |
117,524.1 |
|
|
$ |
67,492.3 |
|
|
All other liabilities |
|
|
1,726.9 |
|
|
|
1,253.3 |
|
|
Total liabilities |
|
|
119,251.0 |
|
|
|
68,745.6 |
|
|
|
|
|
|
|
||||
|
CAPITAL: |
|
|
|
|
||||
|
Capital stock |
|
$ |
4,381.6 |
|
|
$ |
2,292.2 |
|
|
Retained earnings |
|
|
2,398.1 |
|
|
|
2,245.7 |
|
|
Accumulated other comprehensive income (loss) |
|
|
(80.0 |
) |
|
|
33.7 |
|
|
Total capital |
|
|
6,699.7 |
|
|
|
4,571.6 |
|
|
Total liabilities and capital |
|
$ |
125,950.7 |
|
|
$ |
73,317.2 |
|
|
|
For the three months |
For the nine months |
||||||||||
|
Condensed Statement of Income |
|
2026 |
|
|
2025 |
|
|
2026 |
|
|
2025 |
|
|
Total interest income |
$ |
1,240.3 |
|
$ |
998.8 |
|
$ |
3,030.2 |
|
$ |
3,312.7 |
|
|
Total interest expense |
|
1,077.1 |
|
|
853.8 |
|
|
2,586.1 |
|
|
2,827.7 |
|
|
Net interest income |
|
163.2 |
|
|
145.0 |
|
|
444.1 |
|
|
485.0 |
|
|
|
|
|
|
|
||||||||
|
Provision (reversal) for credit losses |
|
1.9 |
|
|
0.4 |
|
|
4.3 |
|
|
1.9 |
|
|
Gains (losses) on investments |
|
(1.9 |
) |
|
0.6 |
|
|
(3.0 |
) |
|
3.7 |
|
|
Gains (losses) on derivatives and hedging |
|
15.9 |
|
|
(6.3 |
) |
|
9.3 |
|
|
(25.9 |
) |
|
Other income |
|
10.7 |
|
|
9.5 |
|
|
27.6 |
|
|
27.4 |
|
|
Other expense |
|
28.8 |
|
|
31.2 |
|
|
89.1 |
|
|
94.7 |
|
|
Voluntary contributions |
|
7.5 |
|
|
9.3 |
|
|
21.8 |
|
|
28.1 |
|
|
Income before assessments |
|
149.7 |
|
|
107.9 |
|
|
362.8 |
|
|
365.5 |
|
|
|
|
|
|
|
||||||||
|
AHP assessment |
|
15.0 |
|
|
10.8 |
|
|
36.4 |
|
|
36.6 |
|
|
Net income |
$ |
134.7 |
|
$ |
97.1 |
|
$ |
326.4 |
|
$ |
328.9 |
|
View source version on businesswire.com: https://www.businesswire.com/news/home/20261021187619/en/
Media gallery

